Market overview of the Fleet Management Market
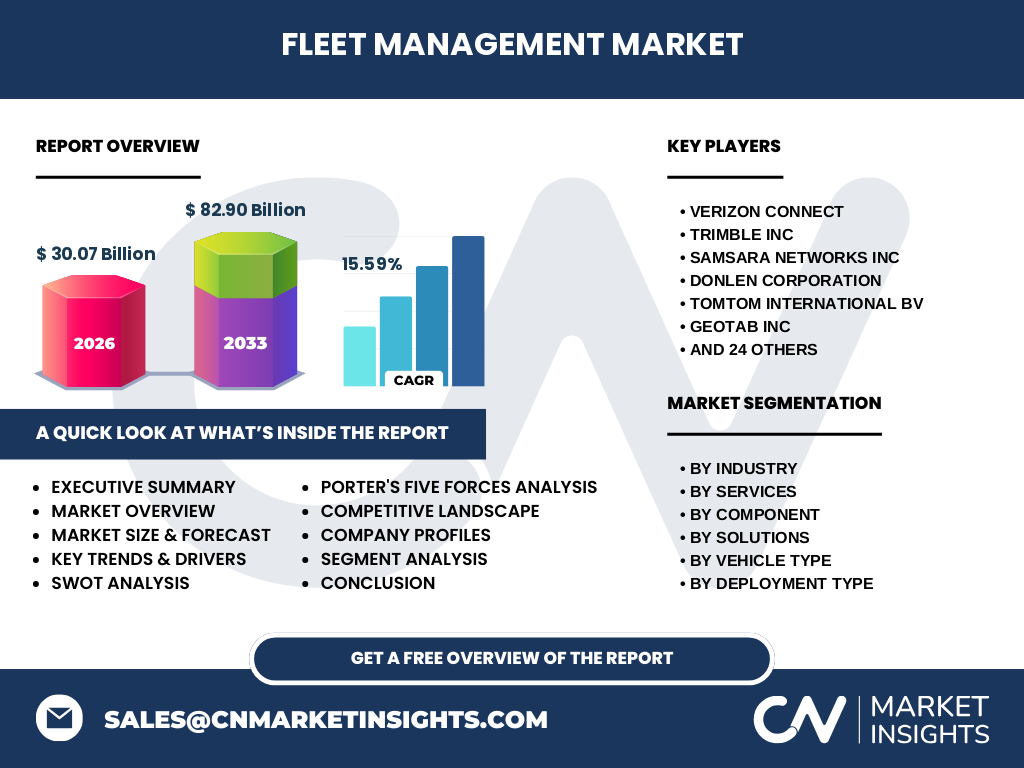
The Fleet Management Market encompasses telematics, software solutions, and hardware designed to oversee commercial transport assets. Valued at 30.07 Billion in 2026, the sector is experiencing a massive valuation surge driven by compliance mandates from agencies like the Federal Motor Carrier Safety Administration and European Union transport directives.
Key market drivers, restraints, challenges, and opportunities shaping the Fleet Management Market
Structural expansion is heavily propelled by the demand for real-time fuel management solutions and strict emission protocols. However, integration friction with legacy heavy commercial vehicles and persistent cybersecurity vulnerabilities act as key operational restraints. Significant opportunities lie in scaling predictive maintenance software across complex multimodal transport nodes.
Emerging trends and growth patterns in the Fleet Management Market
The industry is undergoing a seismic shift toward cloud-native telematics and advanced driver behavior analytics. Our analysis indicates that logistics providers increasingly leverage GNSS satellite tracking alongside cellular networks to eliminate blind spots across remote freight corridors, directly lowering total cost of ownership.
COVID-19 impact analysis and recovery trajectory for the Fleet Management Market
The pandemic severely disrupted supply chains and temporarily halted heavy commercial vehicle production, yet it permanently accelerated the adoption of contactless dispatching. Post-crisis recovery has been exceptionally robust, as enterprises turned to automated route optimization software to navigate volatile demand and severe labor shortages.
Competitive landscape and strategic dynamics in the Fleet Management Market
Market consolidation is intensifying as established giants like Verizon Connect, Trimble Inc, and Samsara Networks Inc acquire specialized telematics providers. Competition centers on proprietary data analytics and reporting services, forcing smaller niche players to carve out defensible positions in localized public transit or municipal government sectors.
Executive summary of key findings for the Fleet Management Market
Our research projects the global Fleet Management Market to reach 82.90 Billion by 2033, expanding at a remarkable CAGR of 15.59% from 2027. This acceleration is heavily anchored in the proliferation of IoT-enabled sensors within commercial light and heavy vehicles.
Market forecast from 2027 to 2033
Accelerating from a 2026 baseline of 30.07 Billion to 82.90 Billion by 2033, the market trajectory reflects a sustained 15.59% CAGR. Adoption of advanced software solutions by retail and logistics giants will fuel this steep growth curve through the end of the forecast period.
Segmentation analysis across industries, services, and components
The market is structurally divided by components into solutions and services, with transportation and logistics commanding the largest industry share. Service revenue is increasingly dominated by specialized implementation, consulting, and maintenance support offerings provided by industry stalwarts like Geotab Inc and Teletrac Navman.
Regional market analysis and geographic performance
Geographic performance is led by North America, supported by rigid federal compliance rules regarding electronic logging devices. Meanwhile, the Asia-Pacific region represents the fastest-growing theater due to exploding e-commerce fulfillment operations and major infrastructure buildouts across logistics hubs in developing economies.
In-depth regional review of the Fleet Management Market
European adoption is heavily influenced by stringent carbon reduction mandates enacted by Brussels, forcing fleet operators to prioritize fuel management solutions. Conversely, North American markets heavily emphasize driver safety and hours-of-service compliance via integrated software platforms deployed across massive transcontinental freight networks.
Company profiles and strategic positioning of leading innovators
Industry leaders such as TomTom International BV and Geotab Inc dominate through open-platform API ecosystems that integrate seamlessly with third-party enterprise resource planning software. Meanwhile, specialized players like KeepTruckin Inc and Azuga Inc maintain competitive moats via driver-centric safety applications and specialized insurance telematics.
Porter's Five Forces analysis of the Fleet Management Market
The industry exhibits high competitive rivalry driven by low switching costs among basic tracking vendors, though advanced AI analytics create strong moats. Buyer power is counterbalanced by the deep integration required for enterprise-grade solutions, while supplier power remains moderate due to specialized GNSS hardware dependencies.
SWOT analysis of the Fleet Management Market
Key strengths include robust recurring software-as-a-service revenue models and indispensable operational visibility. Weaknesses center on hardware obsolescence risks, while prime opportunities involve autonomous vehicle integration. Major threats involve sophisticated cyberattacks targeting critical municipal and commercial transport networks.
Value chain analysis from raw materials to end-users
The value chain flows from semiconductor foundries supplying GNSS and IoT microchips to hardware manufacturers assembling tracking devices. Telematics service providers then process this telemetry data through cloud infrastructure before delivering actionable intelligence to logistics managers and government transport agencies.
Investment insights and high-potential areas
Venture capital and private equity allocations should target proprietary data analytics and reporting services, particularly those incorporating predictive artificial intelligence. Enterprises offering cloud-native SaaS platforms targeting mixed fleets of electric and traditional commercial vehicles present the highest risk-adjusted upside.
Conclusion and key takeaways for stakeholders
The Fleet Management Market is transitioning from basic location tracking to intelligent, autonomous operational control. With a projected valuation of 82.90 Billion by 2033, early adopters of predictive safety and cloud-based asset optimization will capture disproportionate market share.
Research methodology for the Fleet Management Market report
Our baseline estimates are rigorously triangulated by combining proprietary primary stakeholder interviews with C-level executives, exhaustive secondary analysis of trade registry data, and macroeconomic indicators from global transportation ministries to ensure absolute analytical accuracy.
Scope of the report and coverage parameters
This comprehensive analysis covers global deployment types spanning on-premises and cloud architectures, examining aircraft, watercraft, railway, and commercial road vehicles. Limitations exclude unorganized, localized informal transport fleets lacking formal digital instrumentation.
Recent developments, partnerships, and strategic moves
Recent market activity is highlighted by aggressive merger and acquisition strategies among top-tier telematics providers seeking to expand their geographic footprints. Key players are aggressively forging strategic partnerships with automotive OEMs to embed tracking hardware directly onto factory assembly lines.